• LAVA Moderator: streaM Freak

the market: stocks, bonds, options, whatever

If losing money is upsetting, buy ETFs, or don't trade at all if you might need to liquidate within a year.

If you have spare money to play with and are okay going against the grain and making relative valuation comparisons and projecting that based off of what you think the future has in store, make your own picks.

I think that the best advice I can give.
 
If you don't think wall street has already valued into prices what they think you and your mom have done, you are thinking about it wrong!
 
there's a hurricane set to make landfall in U.S. on Friday

make of that what you will
 
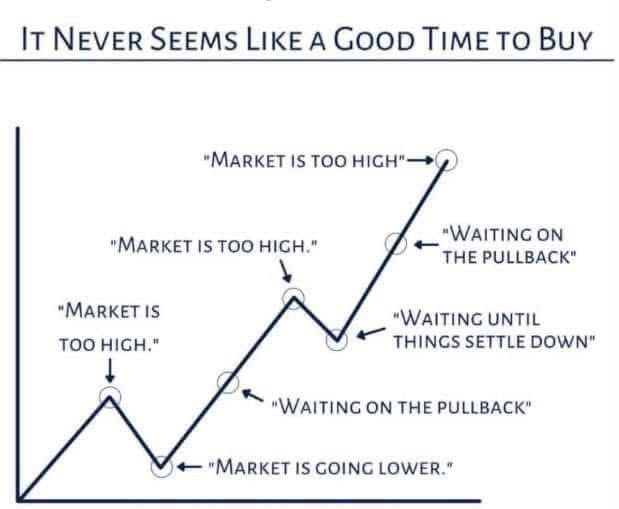
oof, too true

randomwalk.jpg
Dollar cost averaging every month is the only way around this. Otherwise with lump sum investing, especially in individual companies, you're gonna need a huge amount of luck to pick the right timing to invest, even with a a mixture of good judgement, knowledge from 'experts' and a sizeable dollop of picking your timing out of thin air. Although if you have a long enough time horizon it doesnt matter when you invest. If you have 30 years or more, then the chances are that you're gonna come out ahead, even if you initially bought at a peak, just before a huge and prolonged crash. Of course with DCA, as long as you keep paying in through thick and thin, especially through the thin, then in time, things should work out great. They always have done previously.

Obviously this mainly applies to index funds and ETFs. Individual stocks still remain far too risky imo, at least for me with my current level of knowledge. I know my limits, both of my knowledge and understanding, and of the time and effort required, which I just don't have the time, energy, motivation, or interest, to learn enough about individual companies, it's just is not there, and I am therefore sticking to index funds and ETFs, which I understand very well.. Even if and when they go through bad times, they never collapse completely and always recover in time. Historically speaking. The same cannot be said for stocks in individual companies, which can easily loose huge amounts on their share prices, or entirely collapse to nothing, and basically never recover.

The vast majority of actively managed funds do far worse than passive index funds, showing that even people working full time in this occupation, cannot reliably beat the average market returns, by trying to be clever, and by trying to beat the market. This barely ever works, at least never on a consistent basis.
 
Last edited:
If losing money is upsetting, buy ETFs, or don't trade at all if you might need to liquidate within a year.

If you have spare money to play with and are okay going against the grain and making relative valuation comparisons and projecting that based off of what you think the future has in store, make your own picks.

I think that the best advice I can give.
Some of the financial / retirement planning 'influencers' that I watch, advocate using only 10% or so of their total funds for riskier investments, such as crypto, and individual companies.

They do this as a 'bit of fun' with money they can afford to loose.

But they are careful to keep the vast majority of their allocations in the far less risky ETFs and index funds.

The majority don't do crypto or individual companies at all, and put everything into ETFs and index funds, until the time to retirement nears five years or so, and allocations need gradually switching to safer options, that are immune from market crashes.
 
Last edited:
Some of the financial / retirement planning 'influencers' that I watch, advocate using only 10% or so of their total funds for riskier investments, such as crypto, and individual companies.

They do this as a 'bit of fun' with money they can afford to loose.

But they are careful to keep the vast majority of their allocations in the far less risky ETFs and index funds.

The majority don't do crypto or individual companies at all, and put everything into ETFs and index funds, until the time to retirement nears five years or so, and allocations need gradually switching to safer options, that are immune from market crashes.

That's sensible.

There is also a psychological trap in investing in individual stocks, which has happened to be, more than once: when I get on a roll, I can start assuming that I know what I'm doing. And even if I can make predictions or relative valuations better than the Average Joe, there are thousands of high IQ professional traders, companies with inside knowledge, and quant algorithms that basically have everything already valued in to the price.

And even if the stock price is not the fair price, there are people on the market that can make that change at their will. It might not be in their best interest to show their hand and drop or pop a stock in a single day, but that doesn't mean they couldn't if they wanted to.

In conclusion, that's sensible and despite being called an influencer I would nod my head along to that.
 
I wasn't sure of the correct term to use tbh, "youtuber" or "content creator" might have been better. Whatever, I have certainly learnt a great deal from my favorite 3 or 4 financial channels that I watch regularly.

They really know their subject.
 
That's sensible.

There is also a psychological trap in investing in individual stocks, which has happened to be, more than once: when I get on a roll, I can start assuming that I know what I'm doing. And even if I can make predictions or relative valuations better than the Average Joe, there are thousands of high IQ professional traders, companies with inside knowledge, and quant algorithms that basically have everything already valued in to the price.

And even if the stock price is not the fair price, there are people on the market that can make that change at their will. It might not be in their best interest to show their hand and drop or pop a stock in a single day, but that doesn't mean they couldn't if they wanted to.

In conclusion, that's sensible and despite being called an influencer I would nod my head along to that.
Last week I bought a stock that has over 55% short interest and a very high beta, I traded it before and watched it lose 90% when it suddenly whiplashed and I sold for an 80% gain. Maybe I'll make a quick 10% on a short squeeze this time around, maybe I'll lose a little. The only thing I've learned trading is that I never ever doubt my own confidence and my own analytical abilities. Once you starting doubting yourself you give in to fear and lose objectivity. Once you lose objectivity you're basically guessing.
 
Dollar cost averaging every month is the only way around this.

With caveats. For example, if you invest in a pure growth fund that stays flat for a decade that would be worse than DCAing into dividend aristocrats fund that will continue to pay returns.

I started investing heavily during the COVID crash so I've seen right there how impactful it can be to lump-sum at the right time, and I was mainly accumulating dividend funds so I didn't even do as well as if I had invested in pure growth then.

Most of my friends are DCAing into growth or balanced funds so they take the hit every time the market corrects while I'm using that opportunity to sell off dividend funds that held value, and lump-sum aggressively into the growth funds at their 200 day moving average.

Arguably, this approach takes more patience because I have to wait for the correction, which is usually a longer wait than just waiting for the recovery after the drop. But it offers some protection against the tail risk of flat growth for a decade.
I do this with my 'investment account' and then I have a separate 'trading account' for trading.
 
I agree, which is why I am confused by people buying SPY options with a 1 day expiration. If anyone knows why I'd love to hear, because people on webull can't answer me when I ask.

options price can move rapidly, especially when there's not much time value left.

in extreme situations, a contract that costs 25c can pump to $10 in minutes during a squeeze when price moves rapidly

options contracts represent 100 of the underlying so a 25c contract = $25 and at $10 it's worth $1000

the tradeoff is the probability of profit is low but the reward:risk is high enough that it can be profitable even with a low chance of happening

Okay, I think I understand. Sort of like a parlay in terms of probability vs reward.

Sounds like a fun little roll of the dice with fuck-around money.

I think it's pretty funny watching all these "technical analysis" of huge index funds and things that are extremely hard to value like Bitcoin, like someone drawing a support floor on a random number that they see occuring twice then a green arrow going to the sky 😅
 
Top